Figures checked September 2026. Bank and provider fees change, so confirm current terms before you commit.
At most UAE checkouts you now get three ways to spread a payment: Tabby, Tamara, or a 0% installment plan on your credit card. All three promise no interest. All three will happily split AED 2,400 into smaller pieces. So which one should you pick?
When everything goes to plan, they cost about the same. When it doesn't, they differ a lot. What separates them is what happens if you pay late, how each one affects your credit limit and credit report, and whether you lose rewards along the way.
This guide compares Tabby vs Tamara vs bank installments side by side, using figures from each provider's UAE pages, so you can choose based on the purchase in front of you.
Fees and terms change, so treat the numbers here as a guide and check the provider's current terms before you commit.
How each one works
Tabby
Tabby's standard product in the UAE is Pay in 4. You split the purchase into four payments, with the first usually taken at checkout. Tabby states there's no interest or fees on Pay in 4 when you pay on time.
Tabby also offers "Pay over time" plans of up to 12 monthly payments at some stores. Tabby says a service fee may apply to plans longer than four payments, and shows the fee before you confirm.
If you miss a payment in the UAE, Tabby stops you making new purchases until you pay, adds a charge to your account, and may limit your access to its other products. Tabby removed late fees on Pay in 4 in Saudi Arabia in December 2023, but that change was specific to Saudi Arabia.
Tamara
Tamara lets you split a purchase into up to four payments over four months. It markets itself as Sharia compliant, with no interest and no late fees.
Late payments still matter, though. Tamara says repeated late payments can lead to your account being suspended and can affect your credit score.
Bank 0% installment plans
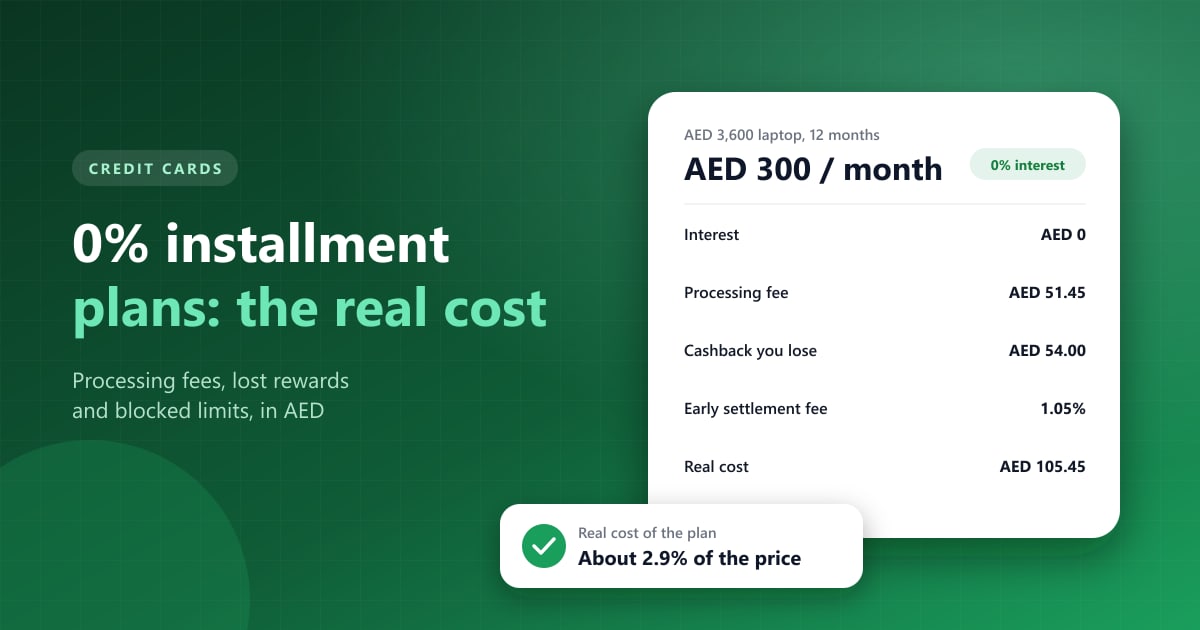
A 0% plan on your credit card splits the purchase into 3 to 24 monthly payments that appear on your card statement. The installment is interest-free, but most banks charge a processing fee. At Emirates NBD it's AED 51.45 including VAT per plan, sometimes waived as a promotion. Rewards are often forfeited on the converted amount, and the full purchase comes off your available credit limit until it's paid down.
If you miss your card payment, you pay your bank's late fee on the whole card (AED 241.50 at Emirates NBD) plus interest on any balance you don't clear. For a full breakdown, see our guide to 0% installment plans in the UAE.
Side-by-side comparison
| Tabby Pay in 4 | Tamara split in 4 | Bank 0% plan | |
|---|---|---|---|
| Interest | None | None | None on the plan |
| Fees if you pay on time | None on Pay in 4; fee may apply on longer plans | None | Processing fee is common (e.g. AED 51.45) |
| Typical length | 4 payments; up to 12 at some stores | Up to 4 payments over 4 months | 3 to 24 months |
| If you pay late | Account paused, charge added | Account can be suspended, credit score affected | Card late fee plus interest on unpaid balance |
| Uses your credit card limit | Only if you pay with a credit card | Only if you pay with a credit card | Yes, full amount blocked |
| Rewards | You earn card rewards if you pay each installment by credit card | Same | Often forfeited on 0% plans |
| Credit report impact | Can affect access and credit | Stated impact on credit score | Reported via your card account |
| Where you can use it | Partner stores online and in-store | Partner stores online and in-store | Partner merchants, or convert eligible purchases in your bank app |
What the same purchase costs with each
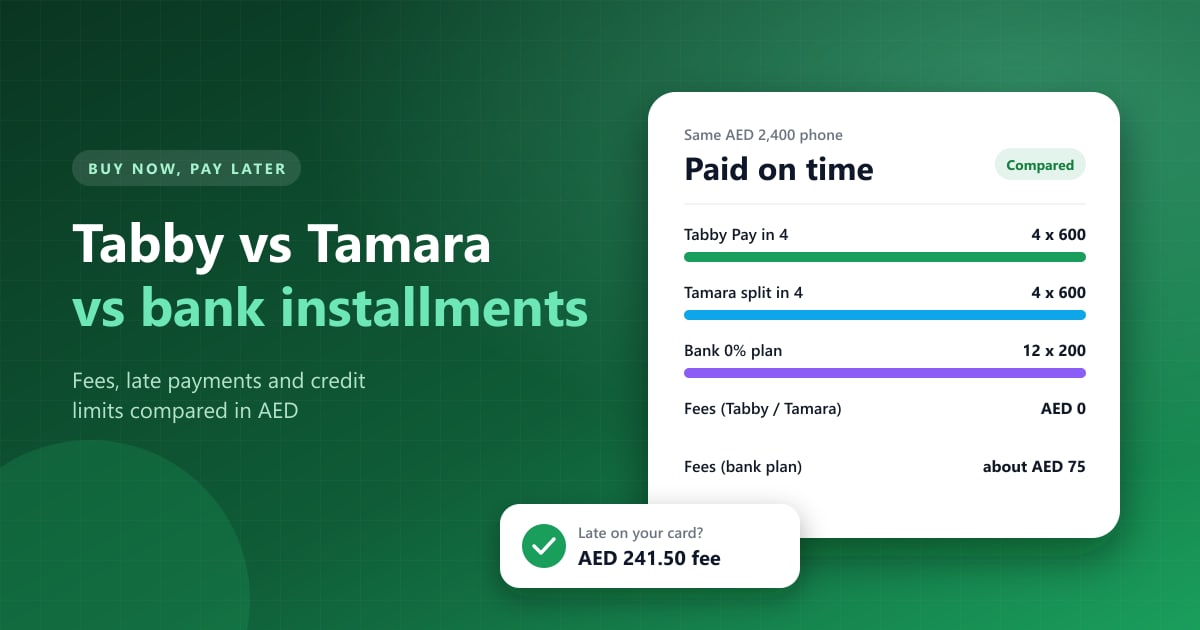
Take a AED 2,400 phone, paid by someone who always pays on time and whose card earns 1 percent cashback.
Tabby Pay in 4: four payments of AED 600. No fees. If each payment is charged to a cashback credit card, you still earn AED 24. Total cost: AED 0, or slightly better than zero if you earn rewards.
Tamara split in 4: the same four payments of AED 600, no fees, same rewards logic. Total cost: AED 0.
Bank 0% plan over 12 months: twelve payments of AED 200, plus a AED 51.45 processing fee, and no cashback on the converted amount. Total cost: about AED 75.
On time, the BNPL apps are cheaper for short plans. The bank plan wins on one thing only: length. AED 200 a month is easier on the budget than AED 600 a month for four months. If you need 12 months to pay comfortably, the bank plan's AED 75 is the price of that breathing room.
Now suppose you miss one payment by two weeks.
- With Tabby, your account is paused and a charge is added until you pay.
- With Tamara, there's no late fee, but repeated delays can affect your credit score and your account.
- With the bank plan, you pay the card late fee, which at Emirates NBD is AED 241.50, and interest on the rest of the statement balance if you haven't cleared it.
The bank option is the most expensive way to be late by a wide margin.
Which should you choose?
Choose Tabby or Tamara when the purchase is modest, you can comfortably pay it off within four months, and you want to avoid processing fees. Between the two, pick the one the store accepts and whose app you'll remember to check. Tamara's no-late-fee policy is gentler if you're worried about slipping, but late payments still have consequences with both.
Choose a bank 0% plan when the purchase is large, you need more than four months to spread the cost, and the processing fee is small compared with the price. It's also the only one of the three that can be applied to a purchase you've already made, through your bank app.
Choose none of them when you can pay in full from money you already have and don't need the flexibility, or when you already have several plans running. Paying cash for something you can afford is always the cheapest option.
Four questions to ask at checkout
Before you tap Tabby, Tamara or your card's installment option, take ten seconds for these:
- Can I pay this off in four months without touching my savings?
- Is the price the same as paying in full, here and at other stores?
- How many installment plans am I already paying, across every app and card?
- Which payment method will I use for each installment, and will I remember the dates?
If any answer makes you hesitate, pay in full or wait.
Returns, refunds and paying early
Returns work differently with each option, and it's worth knowing before you buy something you might send back.
With Tabby and Tamara, a refund from the store goes back through the provider. If the refund is smaller than what you still owe, your remaining payments are reduced. If it's larger, the remaining payments are cancelled and the difference is refunded to you (see Tabby's refund help and Tamara's terms). Refunds can take a few days to show up in the app, so keep paying any installment that falls due in the meantime unless the app shows it's been cancelled.
With a bank 0% plan, the refund is credited to your card, but the plan itself may keep running until the bank closes it. You might need to call the bank to cancel the plan, and some banks charge an early settlement fee when they do. Emirates NBD's fee for closing a plan early is 1.05 percent of the remaining balance.
Paying early is simpler. Both Tabby and Tamara let you settle remaining payments early from the app, with no fee. With a bank plan, check the early settlement fee first, because paying early can cost more than letting the plan run.
Should you use BNPL for everyday spending?
Tabby and Tamara now appear at supermarkets, pharmacies and food delivery apps, not just electronics stores. You can split a AED 400 grocery shop into four payments, but it's rarely a good idea.
Everyday spending repeats. If you split this week's groceries, next week's shop arrives while you're still paying for this one. Within a couple of months, you're paying off the past every time you buy something new, and your budget has shrunk by the total of all those overlapping installments.
A good rule is to use installments only for things that last longer than the payments do. A laptop you'll use for three years can reasonably be paid over four months. A dinner you ate on Tuesday shouldn't still be on your bill in June.
The hidden cost: juggling them all at once
Any single plan is easy to manage. The risk comes from having a Tabby plan for shoes, a Tamara plan for a sofa, and a bank plan for a laptop, each on a different payment date and in a different app.
Take a typical month for someone who says yes at most checkouts. Trainers for AED 800 on Tabby, due on the 3rd. A sofa for AED 3,200 on Tamara, due on the 11th. A phone for AED 3,000 on a 12-month bank plan, due with the card statement on the 20th. Together that's AED 200, AED 800 and AED 250 a month, AED 1,250 in all, spread across three apps and three dates. The payment that gets missed is rarely the biggest one. It's the one that lands two days before payday, in the app nobody opened that week.
That's how people end up with AED 1,500 a month going out in small installments without ever deciding to spend AED 1,500 a month. It's also how payments get missed: none of them is hard to pay, but there are too many dates to keep track of.
A few habits prevent this:
- Keep one list of every active plan across Tabby, Tamara and your cards, with the monthly amount and end date.
- Treat the total as a fixed bill in your monthly budget, not as variable spending.
- Set a cap on how much of your take-home pay can go to installments. Ten percent is a sensible starting point.
- Pay BNPL installments from a credit card you clear in full each month. You earn rewards, and the card's statement cycle gives you extra time without interest.
- Turn on payment reminders in every app you use.
Fixpenses lets you log each installment as it happens and see all your commitments in one place, whichever app or card they're on. You can track every expense in AED and spot the moment your installments start creeping up.
Frequently asked questions
Is Tabby or Tamara better?
For a short plan paid on time, they cost the same: nothing. Tamara advertises no late fees at all, while Tabby's UAE Pay in 4 can add a charge if you miss a payment. Tabby also offers longer plans of up to 12 payments at some stores, which may carry a fee.
Do Tabby and Tamara check my credit?
Both assess whether to approve each purchase, and both say late payments can affect your account and credit. Treat them like any other credit product.
Can I pay Tabby or Tamara with a credit card?
Yes, both accept cards. Paying installments with a credit card you clear in full each month lets you earn rewards and adds a little breathing room, as long as you never carry that balance.
Which is best for a large purchase like a TV or laptop?
For purchases you need more than four months to pay off, a bank 0% plan usually works better, because the monthly amount is smaller. Check the processing fee and whether the store's price matches other retailers first.
The bottom line
Tabby, Tamara and bank 0% plans are all interest-free when you pay on time. For short plans, the BNPL apps usually cost nothing, while the bank plan costs a processing fee and your rewards. For longer plans, the bank's fee buys you smaller monthly payments.
Which provider you use matters less than whether the installment fits your budget and whether you'll remember to pay it. Before your next checkout, add up what you're already paying across every plan. If the total is comfortable, pick whichever option suits the purchase. If it isn't, the cheapest choice is not to split it at all.